Sugs Lloyd H1 FY27 Results: PAT up 69%, Strong FY28 Guidance
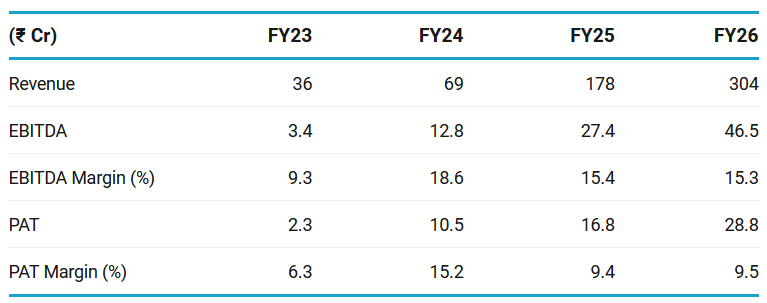
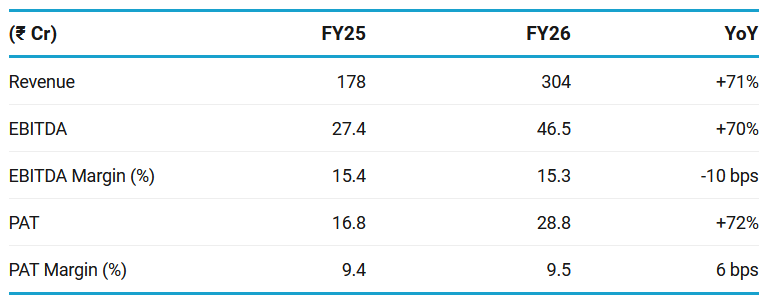
Guiding 100% revenue growth in FY27. FY26-28 revenue CAGR of 80%. Valuations are cheap. Opportunity of re-rating multiples. Quality of earnings is a problem
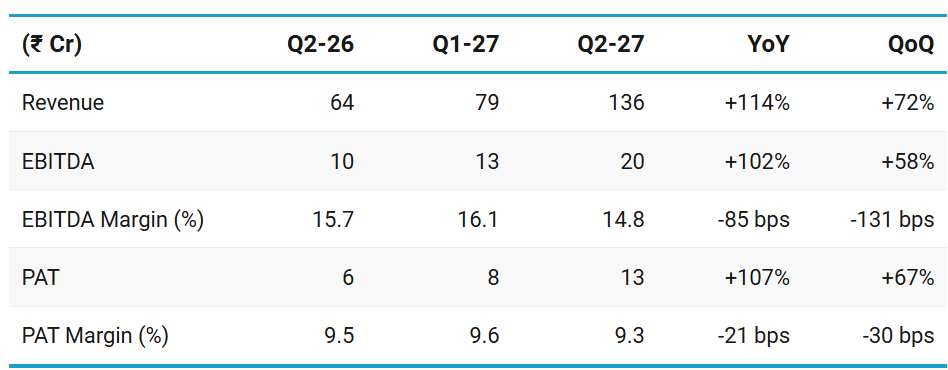
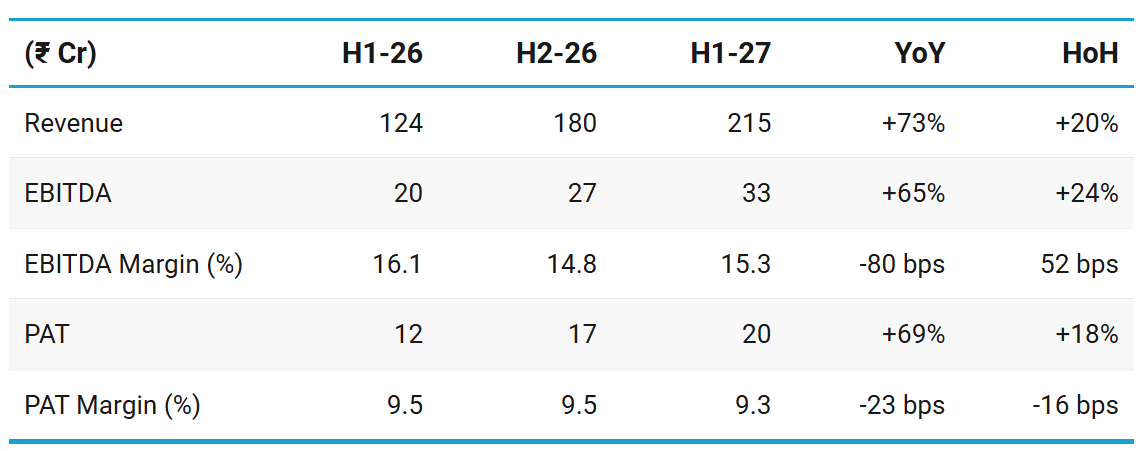
In the second quarter alone revenue rose 112% to ₹134.9 Cr, carrying both the quarter's own billing and the June billing that moved from Q1 into Q2, as indicated on the Q1 earnings call.
5. H1 FY27: PAT up 69% & Revenue up 73% YoY
PAT up 18% & Revenue up 20% HoH
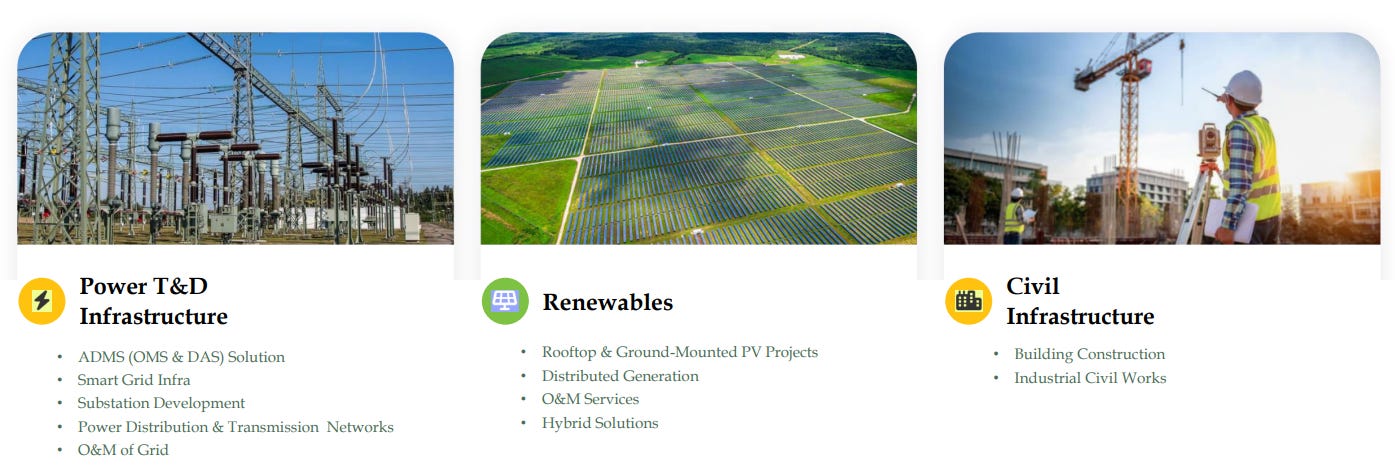
Growth was led by the Power T&D and Smart Grid vertical, which contributed 80% of H1 revenue against 46% in FY26. Solar EPC contributed 20% of revenue
6. Business Metrics: Stable Return Ratios
7. Outlook: Growing at 70%+ CAGR
7.1 FY27 Guidance
FY27 Guidance as of Q1-27 Earnings call:
As of 30 September, our total order book stood at ₹1,068 crore, comprising ₹929 crore in Power T&D and ₹139 crore in Solar.
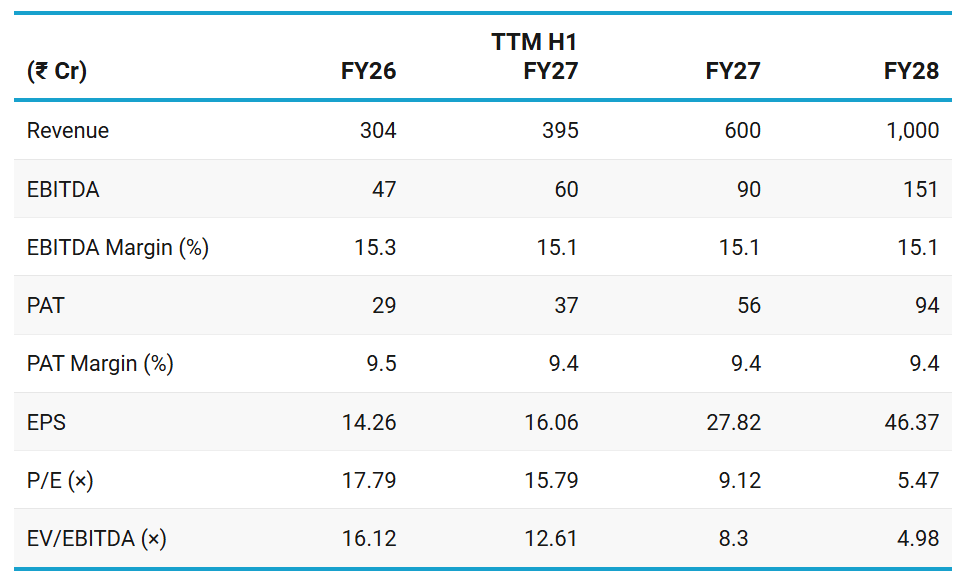
FY28 as of H1-27: Management has set out a guidance of revenue of ₹1,000 crore for FY 27-28.
7.2 H1 FY27 Performance vs FY27 Guidance
The execution risk is very high as asking rate for H1 is ₹385 Cr for H2 vs ₹215 Cr revenue achieved in H1
Quarterly run-rate needs to scale up from ₹135 Cr in Q2-27 to ₹192.5 Cr for the remaining quarters.
Management has indicated that execution of FY27 guidance will be back loaded into Q4. Any slippages within Q4 means that FY27 guidance is not achieved.
Our business remains weighted to the March quarter.
The order book of ₹1,068 Cr provides the revenue visibility to deliver on the ₹600 Cr target for FY27
8. Valuation Analysis — Sugs Lloyd
8.1 Valuation Snapshot
Current Market Price — ₹253.65
Market cap — ₹588.82Cr
Sugs Lloyd looks optically very cheap on FY27/FY28 earnings if management hits the ₹600 Cr / ₹1,000 Cr revenue path.
Sugs Lloyd is being valued like a Solar EPC while underlying business has shifted towards Power T&D and Smart Grid
20% of its revenue came from Solar EPC
8.2 Opportunities at Current Valuation
Current and forward valuation is not demanding
Forward valuation becomes very cheap if FY27/FY28 guidance is met
Nature of business has changed — no long a solar EPC — may get re-rated with better multiples
Power T&D and Smart Grid vertical, 80% of H1 revenue against 46% in FY26.
Solar EPC contributed 20% of H1 revenue against 52% in FY26.
87% of order book is for Power T&D
Order book of ₹1,068 Cr, comprising ₹929 Cr in Power T&D and ₹139 Cr in Solar
Order book of ₹1,068 Cr, provides revenue visibility up to H1 FY28
Opportunity is not just earnings growth. It is earnings growth + multiple re-rating.
8.3 Risks at Current Valuation
Cash flow risk — H1 FY27 cash flow from operations was negative despite strong PAT.
Receivable risk — receivables at ₹191 Cr are very high relative to H1 FY27 revenue of ₹215 Cr.
Execution risk — revenue has to move from ₹300 Cr to ₹600 Cr to ₹1,000 Cr very quickly.

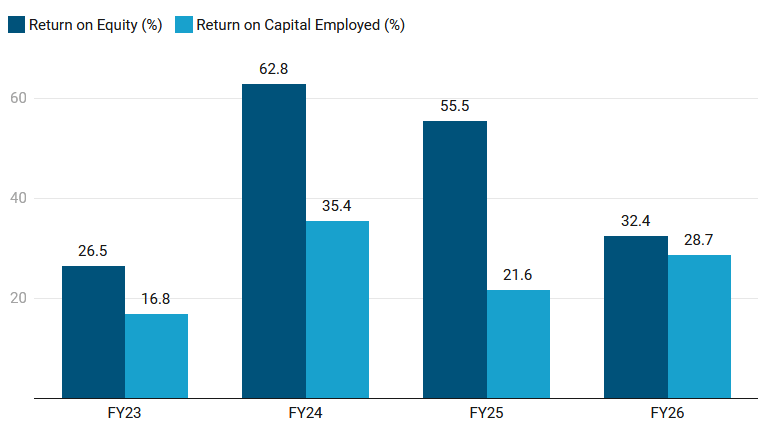


management's own benchmark for distribution work is around 180 debtor days industry wide, and it doesn't see that coming down quickly
with t&d and smart grid now 80% of sales, the receivable load grows with the same mix that drives the rerating case