
1. Exporting Preserved Gherkins & Pickled Vegetables
fresharaagroexports.com | NSE - SME: FRESHARA
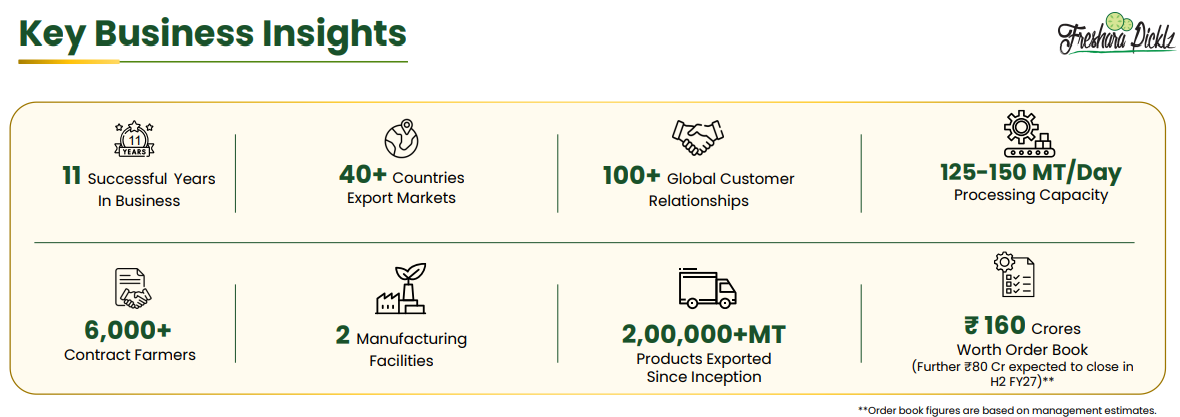
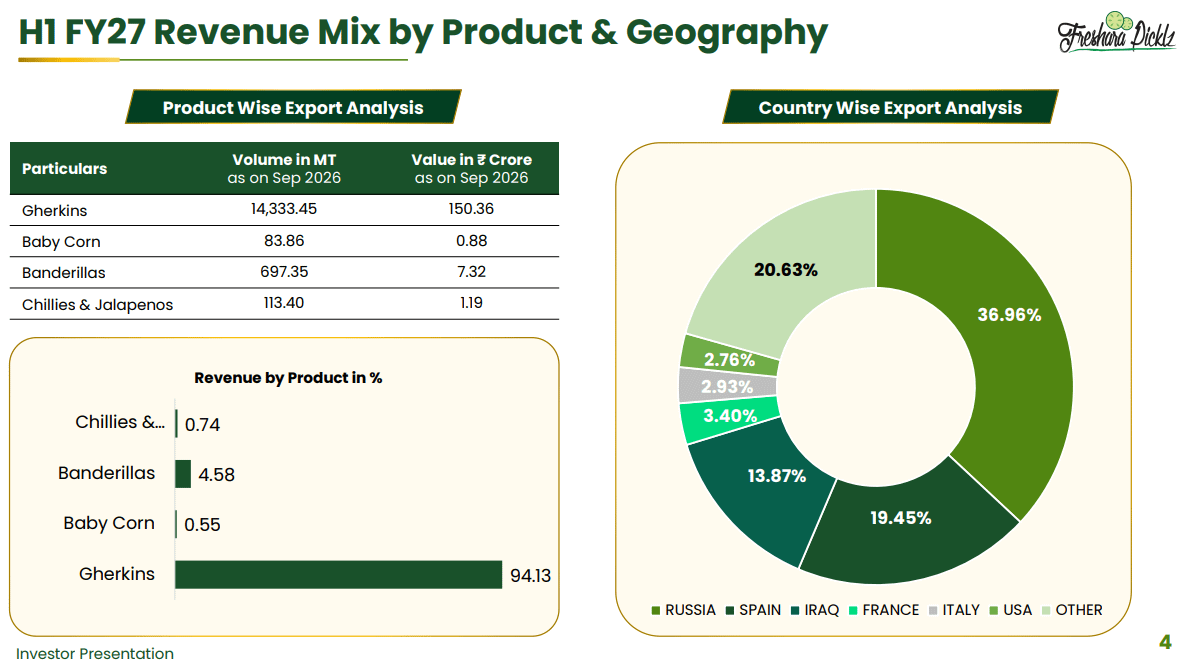
3rd Largest Gherkin Exporter
2. FY22–26: PAT CAGR of 149% & Revenue CAGR of 31%
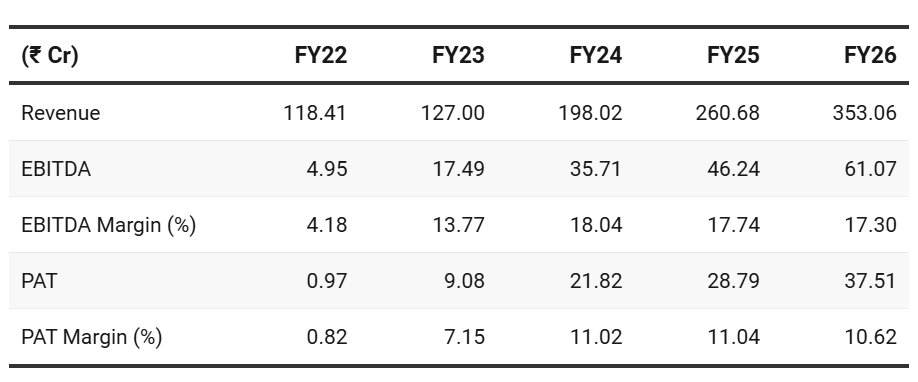
3. FY26: PAT up 30% & Revenue up 35% YoY

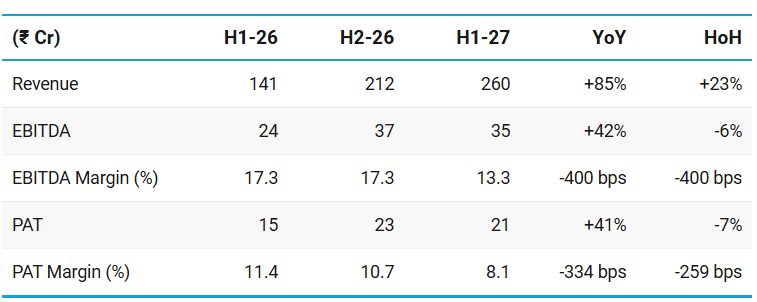
4. H1 FY27: PAT up 41% & Revenue up 85% YoY
PAT down 7% & Revenue up 23% HoH
Standalone (Freshara India)
EBITDA Margin = 13.63% | PAT Margin = 8.09%
Ocean freight rates went ~3x in Q2 - impacting the margins of India business
Margins expected to improve in H2 FY27 as freight rates have started colling off
Sarasa and Gandin (Spain)
EBITDA Margin = 12.3% | PAT Margin = 7.44%
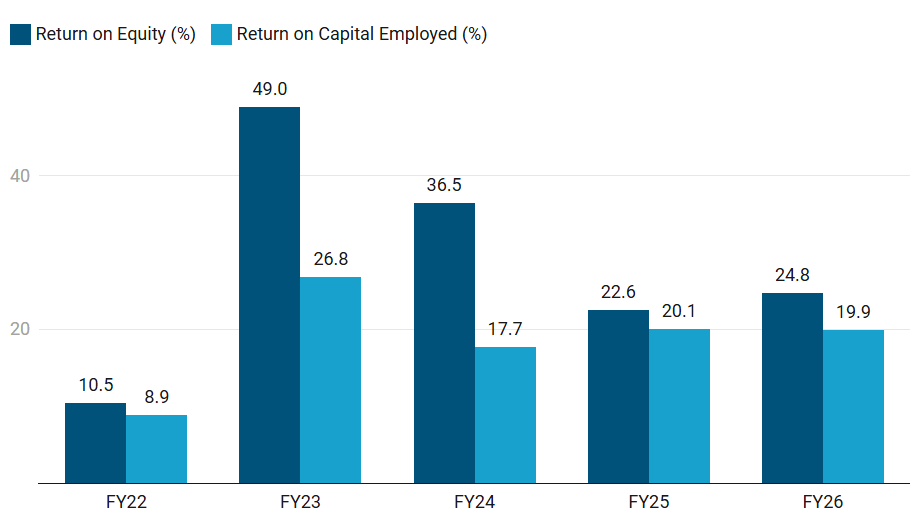
5. Business Metrics: Strong Return Ratios
6. Outlook: Revenue CAGR of 40%+ for FY26-30
6.1 Management Guidance — Freshara Agro Exports
FY27: Revenue = ₹570-600 Cr
India business = ₹400 Cr
Spain business = ₹170-200 Cr
Management confident of achieving revenue targets as order book is in place and capacity is already booked for the next 6 months
FY28 Revenue Target = ₹750 Cr
30% organic growth
Evaluating potential processing acquisitions in India under ₹50 Cr
Inorganic growth if any will be additional to the 30% target
FY29 Revenue Estimate ~₹1,000 Cr
₹1,000 Cr target of FY30 being moved forward
Maximum revenue potential = ₹1,500 Cr
India = ₹1,000 Cr + Spain = ₹500 Cr
Peak revenue margins
EBITDA margin =14–15%
PAT margins =10–11%.
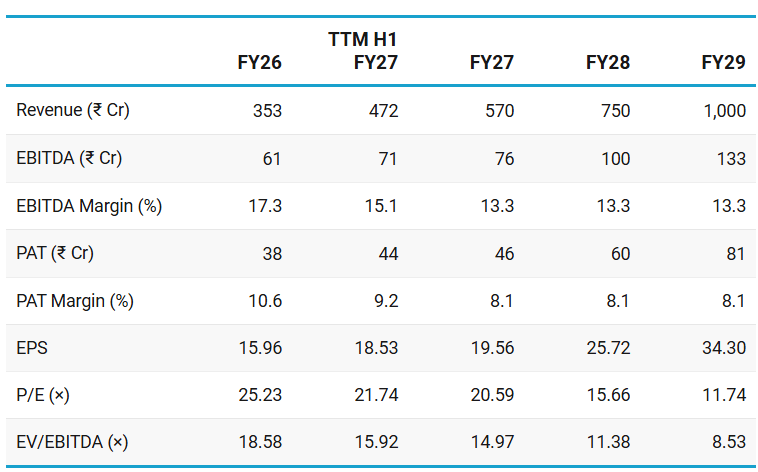
Freshara scaling from ₹353 Cr in FY26 to ₹1,000 Cr by FY30 implies a revenue CAGR of 41%
7. Valuation Analysis
7.1 Valuation Snapshot — Freshara Agro Exports
CMP ₹402.75;
Mcap ₹946.43Cr;
Attractive Valuations:
Freshara is reasonably valued based on FY27 PE (×) of 22
Freshara start looking attractive on FY28 PE (×) of 16,
Forward valuations multiples provide opportunity of re-rating given the business is expected to growth at ~30%.
At peak revenue without any in-organic growth the business is expected to deliver ₹1,500 Cr revenue at a PAT margin of 10-11%.
A PAT of ₹150 Cr with a conservative PE (×) of 20 implies a market cap of ₹3,000 Cr i.e. ~3×+ from the current market cap
7.2 Opportunities at Current Valuation
The forward outlook and guidance provided by the management is not fully discounted in the price
Management is looking at opportunities for in-organic growth.
Targeting smaller, underutilized food processing plants with strong contract farming networks (e.g. in Karnataka/Tamil Nadu) and sticky international clients.
To spend ~₹50 Cr for a unit capable of generating ₹150+ Cr revenue
Allocation of ~₹50 Cr is planned alongside ₹30-50 Cr of working capital over the next 12-month period.
Transition of the the business from bulk industrial packing toward retail packaging and consumer-branded products expected to drive margins form current 8% PAT to 10-11% PAT
7.3 Risks at Current Valuation
The risk is in the execution. The roadmap towards peak revenue of ₹1,500 Cr revenue goes up to FY31.
It will require year on year strong execution
At current valuations the margin of safety if slippages happen is limited
Integration risk — Spanish acquisitions
Initial results from the Spanish business are positive however one needs to watch out how the Psanish business scales up from the current ₹200 Cr run-rate to the peak revenue of ₹500 Cr.
The current scale of business provides for limited ability to absorb external shocks as seen in the week margin performance in H1 FY27 on account of freight costs
As an export oriented business it is susceptible to geo-political shocks.
Previous Coverage of Freshara Agro Exports Ltd

Don’t like what you are reading? Let us know at hi@moneymuscle.in
Don’t miss reading our Disclaimer