
1. WTicabs — Fleet Solutions for Corporates
wticabs.com | NSE: WTICAB
80%, 85% of our business comes from B2B, that means our corporate clients
The second part of the business is self-drive business, which we have started in Dubai, where we buy cars and give it on self-drive to various customers
The third part of the business is where we are partnering with Uber to provide Uber Black Fleet
We are the largest provider of Uber Black Fleet to Uber, where we buy the cars, then we manage the complete operations and the driver is on our revenue sharing model
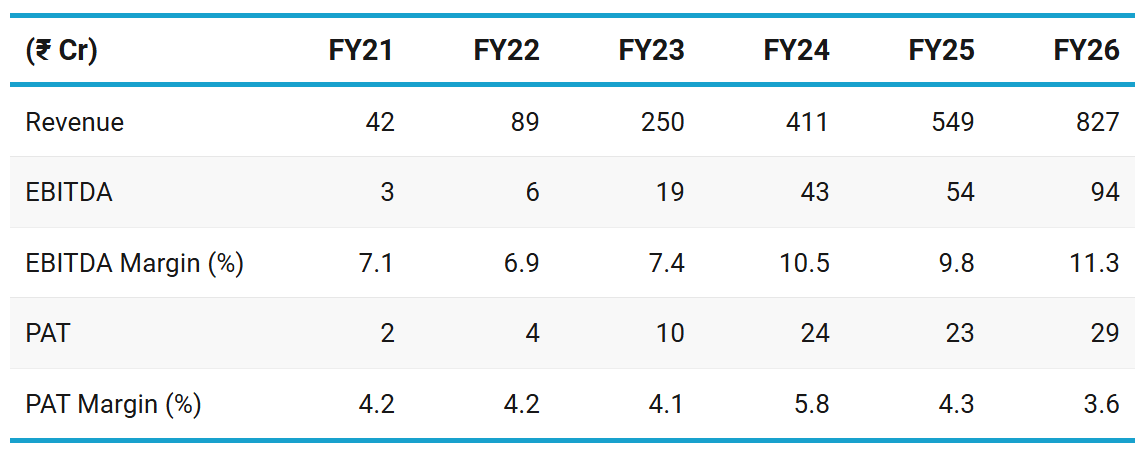
2. FY21–26: PAT CAGR 155% & Revenue CAGR 81%
3. FY26: PAT up 26% & Revenue up 51% YoY
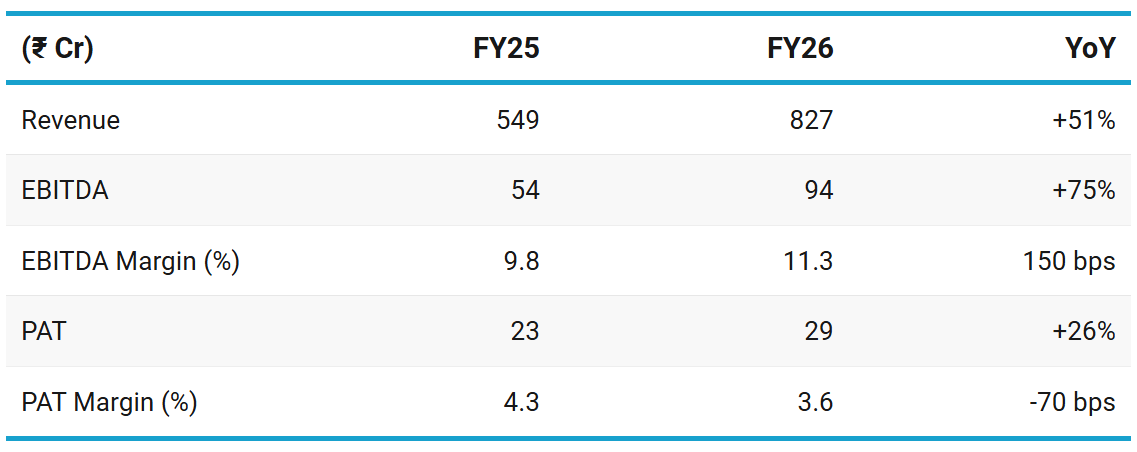
PAT margin declined
Higher depreciation: Substantial investment in owned vehicles — owned fleet increased from 1,226 to 1,932 vehicles
approximately 1000 vehicles are with Uber, 400 vehicles are for self-drive in Dubai, balance around 500 vehicles are with our various corporate accounts
Interest expenses doubled as borrowings increased to finance fleet expansion
New vehicles require time for registration, driver deployment and operational stabilization
Depreciation and financing costs incurred before vehicles achieve full revenue-generating potential
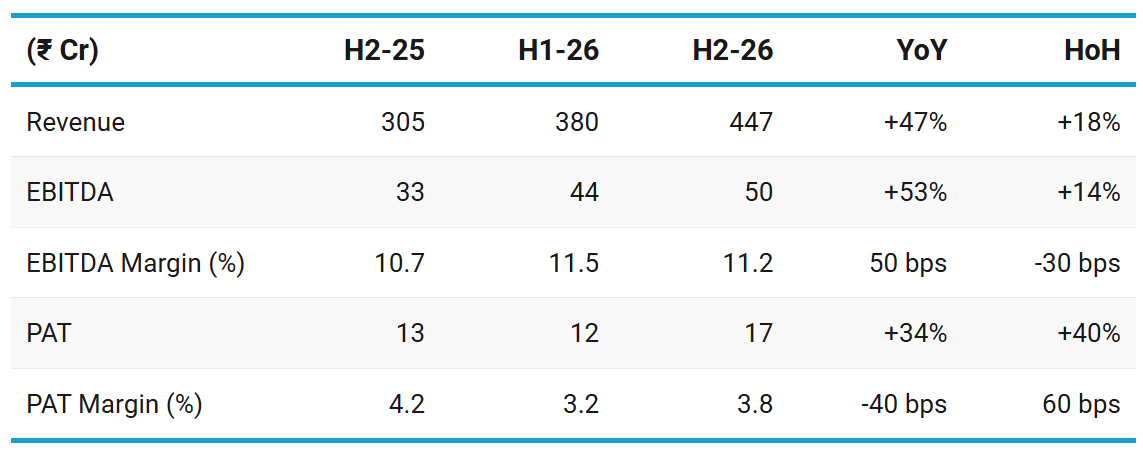
4. H2 FY26: PAT up 34% & Revenue up 47% YoY
PAT up 40% & Revenue up 18% HoH
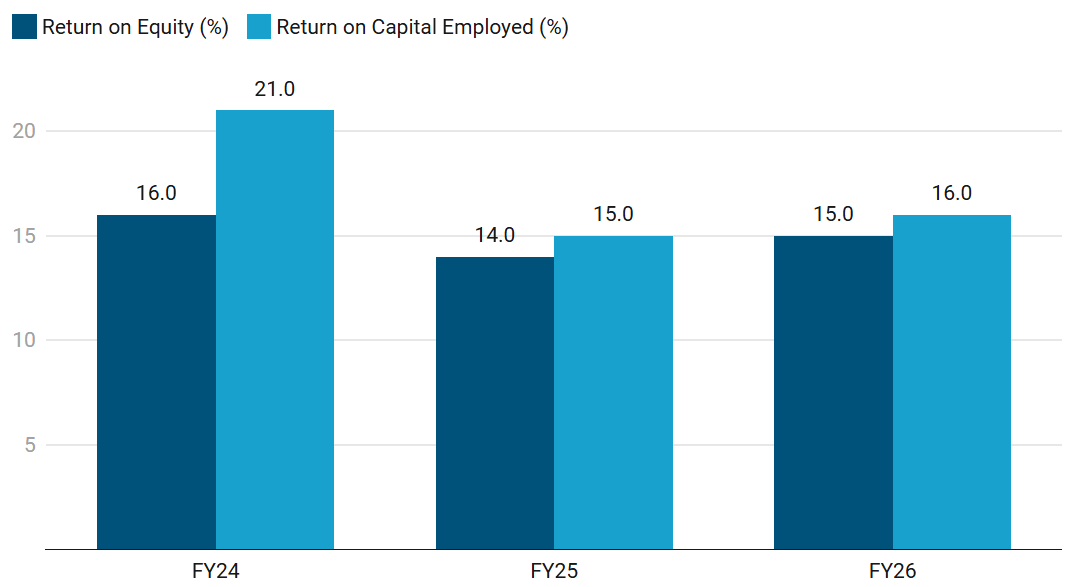
5. Business Metrics: Reasonable Return Ratios
6. Outlook: 35-40% Revenue CAGR
6.1 Management Guidance — Wise Travel
WTicabs aims to attain a revenue CAGR of 35–40% through strategic investments, emphasizing Employee Transportation Services, Car Rental Services, & the consolidation of operations in 250+ cities, ultimately establishing a significant global presence.
PAT margin should be around 5% to 7%. And EBITDA -- again, consolidated EBITDA should be somewhere around 20% to 25%.
7. Valuation Analysis
7.1 Valuation Snapshot — Wise Travel
Current Market Price= ₹97; Market Cap = ₹230.97 Cr
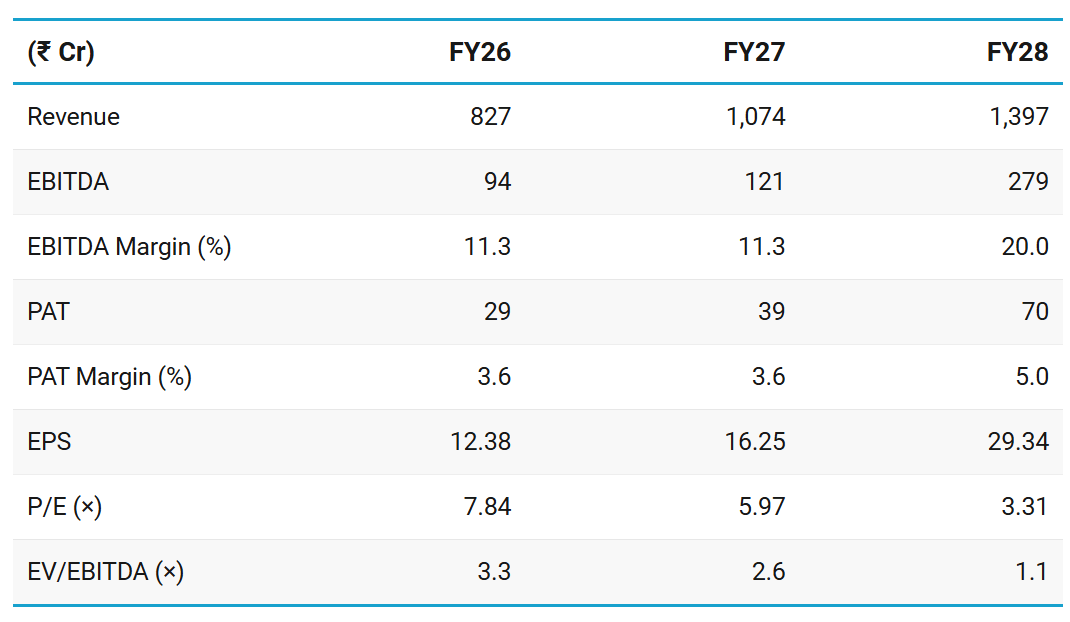
WTICAB has guided for FY27 growth similar to the 35-40% growth with EBITDA margin of 20-22% and PAT margin of 5-7%
Assumed conservative 30% growth in FY27 without any margin expansion
Assuming FY27 guided margins actually getting delivered in FY28 with 30% growth
Talking about our balance sheet strength, our net worth has increased from INR172 crores to INR201 crores
Looks cheap at current prices
New worth of ₹201 Cr trading at market cap of ₹230.97 Cr implies a P/B of 1.15(×)
FY26 sales of ₹826.53 Cr at market cap of ₹230.97 Cr implies a P/S of 0.28(×)
FY26 P/E (×) of 7.8 and EV/EBITDA (×) of 3.3
Cheap forward valuations with FY28 P/E (×) of 6 and EV/EBITDA (×) of 2.6 for a company delivering 35-40% growth
7.2 Opportunity at Current Valuation
Cheap historical earnings multiple: 7.84(×) FY26 earnings
Cheap for 51% revenue growth and 26% PAT growth.
Valued at only 0.28x annual revenue.
Earnings acceleration:
Guidance of 30–35% FY27 revenue growth and 5–7% PAT margins.
Bottom-line to grow faster than top-line.
Operating leverage from recently acquired vehicles:
As new vehicles mature, higher utilization could increase earnings without a proportionate rise in fixed expenses.
Improving operating cash generation:
Cash flow from operations increased from approximately break-even in FY25 to more than ₹52 Cr in FY26.
Cash generation could support expansion and reduce reliance on incremental borrowings.
Potential valuation re-rating:
If WTICAB demonstrates PAT margin recovery and strong cash conversion, markets may assign a higher earnings multiple than the current 7.84x.
7.3 Risk at Current Valuation
Aggressive profitability guidance: Management expects strong margin expansion with FY27 consolidated EBITDA margins of 20–25% and PAT margin of 5-7%.
Such a large margin expansion has not been demonstrated historically
Potential value-trap risk: If additional capital expenditure and depreciation continue to absorb operating profits as in FY26, WTICAB could remain on a low earnings multiple despite strong revenue growth.
Don’t like what you are reading? Will do better. Let us know at hi@moneymuscle.in
Don’t miss reading our Disclaimer