
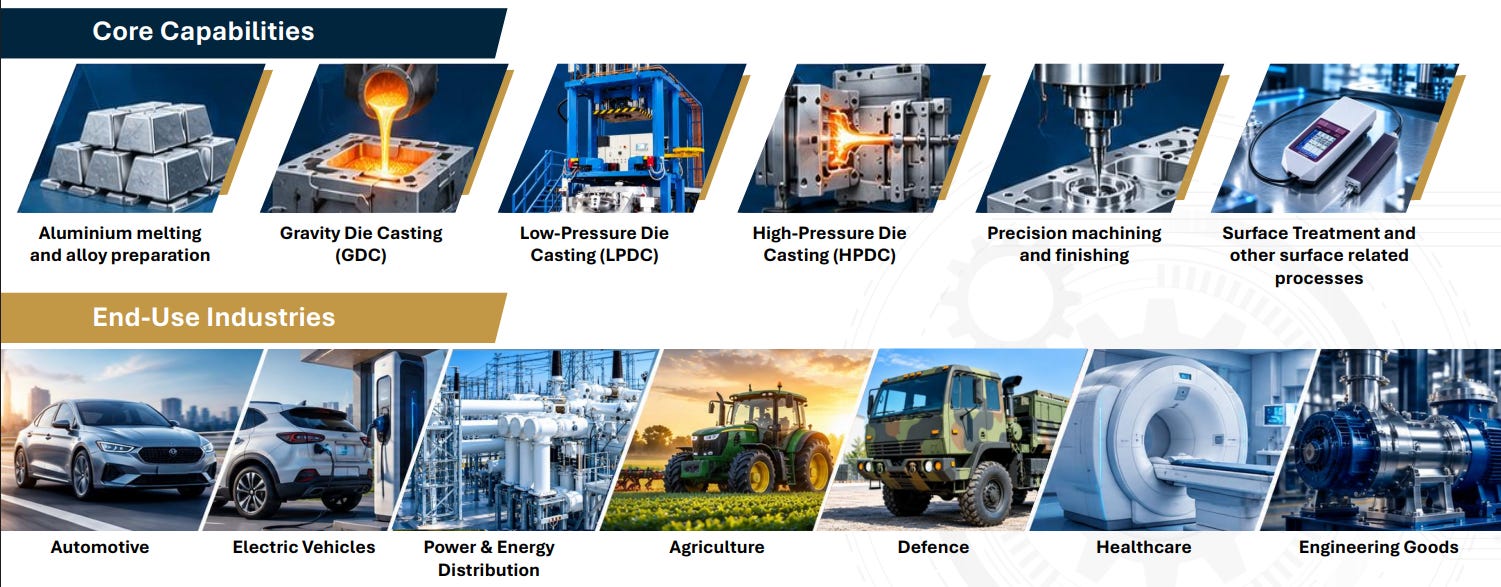
1. Precision-Engineered Aluminium Components
poojaaprecisionengg.in | BSE - SME: 544844
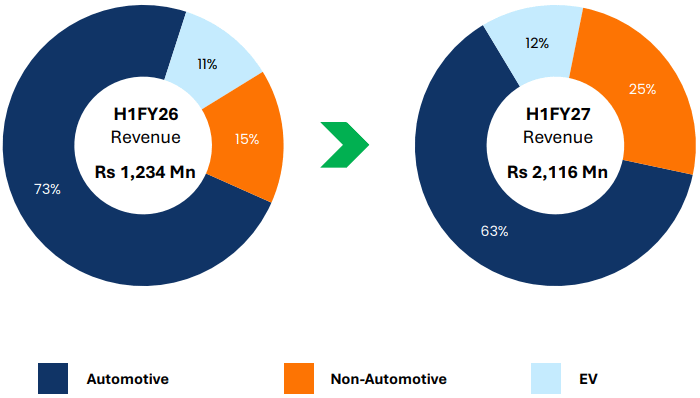
Revenue Split
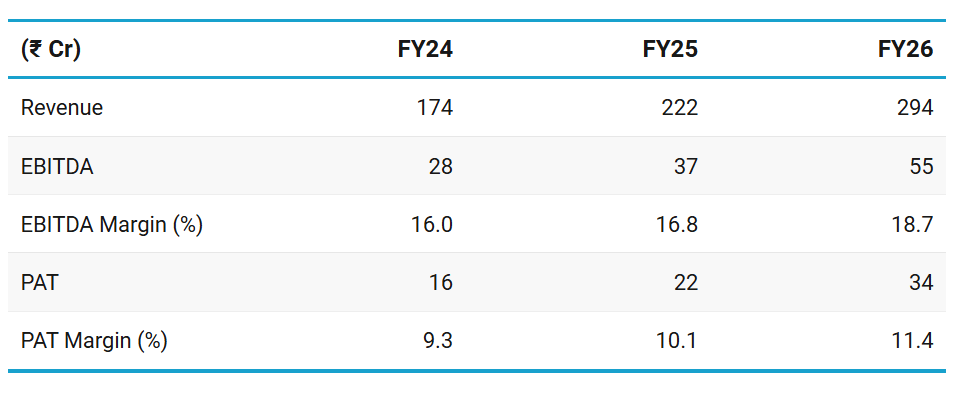
2. FY24-26: PAT up 44% & Revenue up 30% CAGR
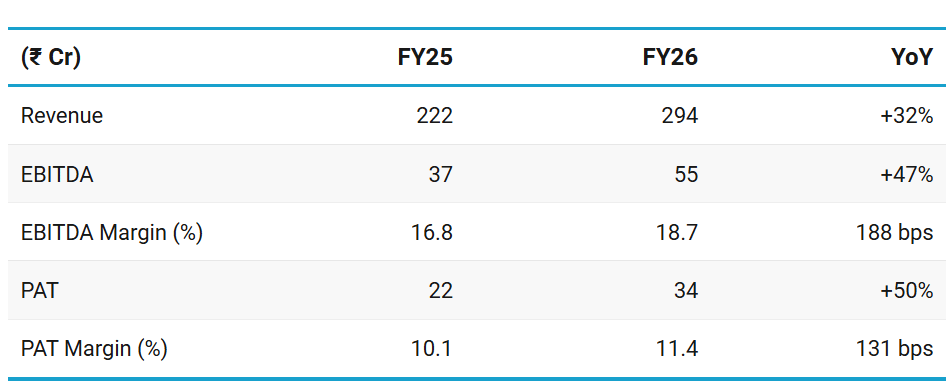
3. FY26: PAT up 50% & Revenue up 32% YoY
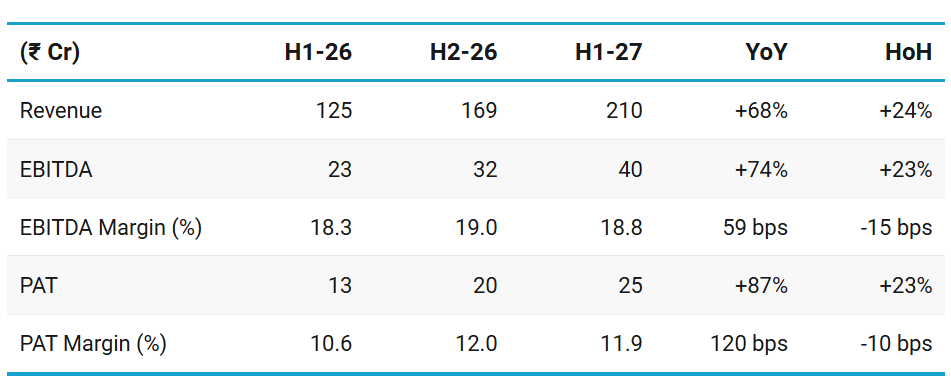
4. H1 FY27: PAT up 69% & Revenue up 73% YoY
PAT up 18% & Revenue up 20% HoH
5. Business Metrics: Stable Return Ratios
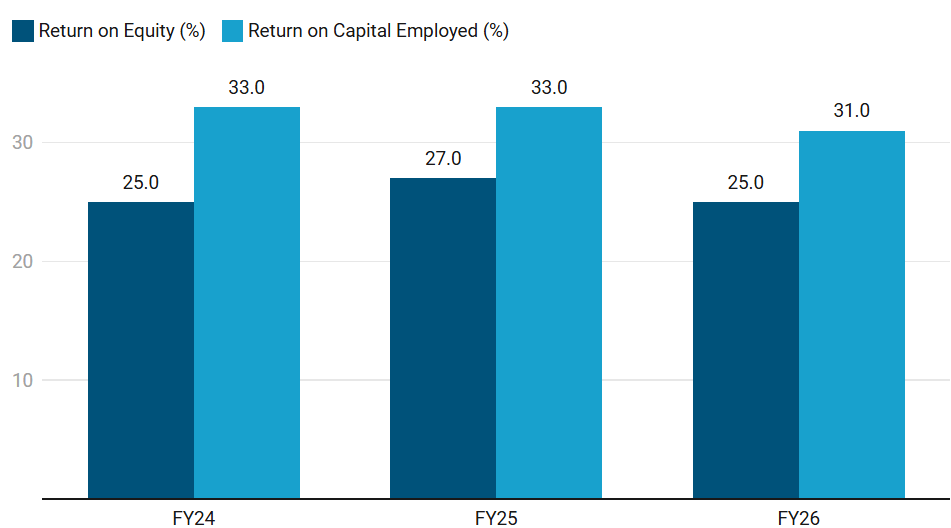
In spite of raising 50% of our capital in August, our ROE is strong at 25%, supported by robust balance sheet with a low debt-to-equity ratio of 0.08x and fixed asset turnover of 4x, reflecting efficient asset utilization and strong revenue generation.
6. Outlook: 50% Growth in FY27
6.1 Guidance & Future Outlook
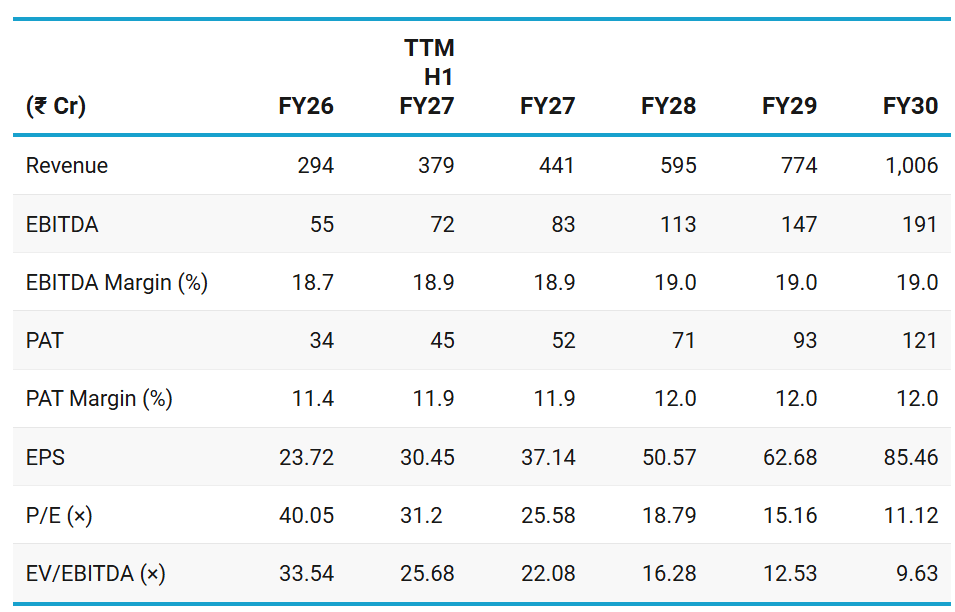
Supported by our capacity expansion and order books, we are targeting 50% revenue growth in FY27 and expect to grow at the range of around 30% to 35% for the coming two years with a clear objective of achieving INR1,000 crores in annual turnover by FY30.
We are backed by a robust order booking of almost INR1,180 crores, giving us strong revenue visibility over the coming financial year.
Currently, order book position is very strong, which is INR1,180 crores to be executed in next two years' time.
With this momentum expected to continue into H2FY27, we expect to sustain
EBITDA margins of ~19%
PAT margins of ~12%.
There will be no additional capacity required. Whatever we are installing right now, this will be quite sufficient for the INR1,000 crores to achieve by 2030.
6.2 H1 FY27 Performance vs FY27 Guidance
On-track to deliver FY27 guidance
We can see it's not conservative. It's highly achievable, 50% growth CAGR over the last year numbers.
To achieve the ₹441 Cr revenue target for FY27, the asking rate is ₹231 Cr for H2 which is nit significantly higher than the ₹210 Cr achieved in H1
Order book supports the revenue target for H2 FY27
The order book of ₹1,180 Cr provides the revenue visibility to deliver the guidance till H1 FY29
7. Valuation Analysis — Poojaa Precision Engg.
7.1 Valuation Snapshot
Current Market Price — ₹950
Market cap — ₹1,894 Cr
Poojaa Precision looks reasonable on FY27 earnings at a P/E of 26× and EV/EBITDA of 22× and if management delivers on the 50% growth target.
Poojaa Precision starts looking very attractive if from FY28 onwards if the 30-35% growth starts getting delivered.
If we assume 30× multiple on FY30 PAT of ₹120 Cr we arrive at a market cap of ₹3,600 Cr which is ~2× from the current market cap i.e. 20%+ CAGR opportunity.
7.2 Opportunities at Current Valuation
The opportunity is in the longer-term growth guidance of 30-35%
If margins expand as indicated by management bottom-line could grow faster than the 30-35% growth in the top-line
We are planning to repay the entire loan by this second quarter and we are going to have very minimal finance cost for that. And moving forward, the PAT margins are going to increase because we have already done the fixed cost. Entire fixed cost has been already incurred. The variable cost is to be incurred, so we think, moving forward, it will be getting much better, the PAT margins.
Now we are getting bigger-sized products, like 50 kg, like 80 kg. Earlier it was in the range of 1 kg to 9 kg. So, wherever the product mix changes and where the raw material components increases, the gross margin seems to be on downside, but overall margins will always remain higher.
7.3 Risks at Current Valuation
Margin of safety is limited at current prices
FY27 guidance is already in the price and Poojaa Precision looks reasonable on FY27 earnings
The risks is in the execution of the guidance till FY30
The risk is mitigated to the extent that revenue visibility is in-place till H1 FY29.
One needs to watch how the ~₹1,400 Cr of order-book gets built in place to provide revenue visibility of the ~₹400 Cr revenue for H2 FY29 and ~₹1,000 Cr revenue for FY30
Help your group stay ahead. Share now!
Don’t like what you are reading? Let us know at hi@moneymuscle.in
Don’t miss reading our Disclaimer
the rfq math from the h1 call gives 160-180 cr of new wins a year, which looks thin next to what still has to be built
what yearly order win would you need to see by fy28 before fy30's 1,000 cr still holds on your model?