
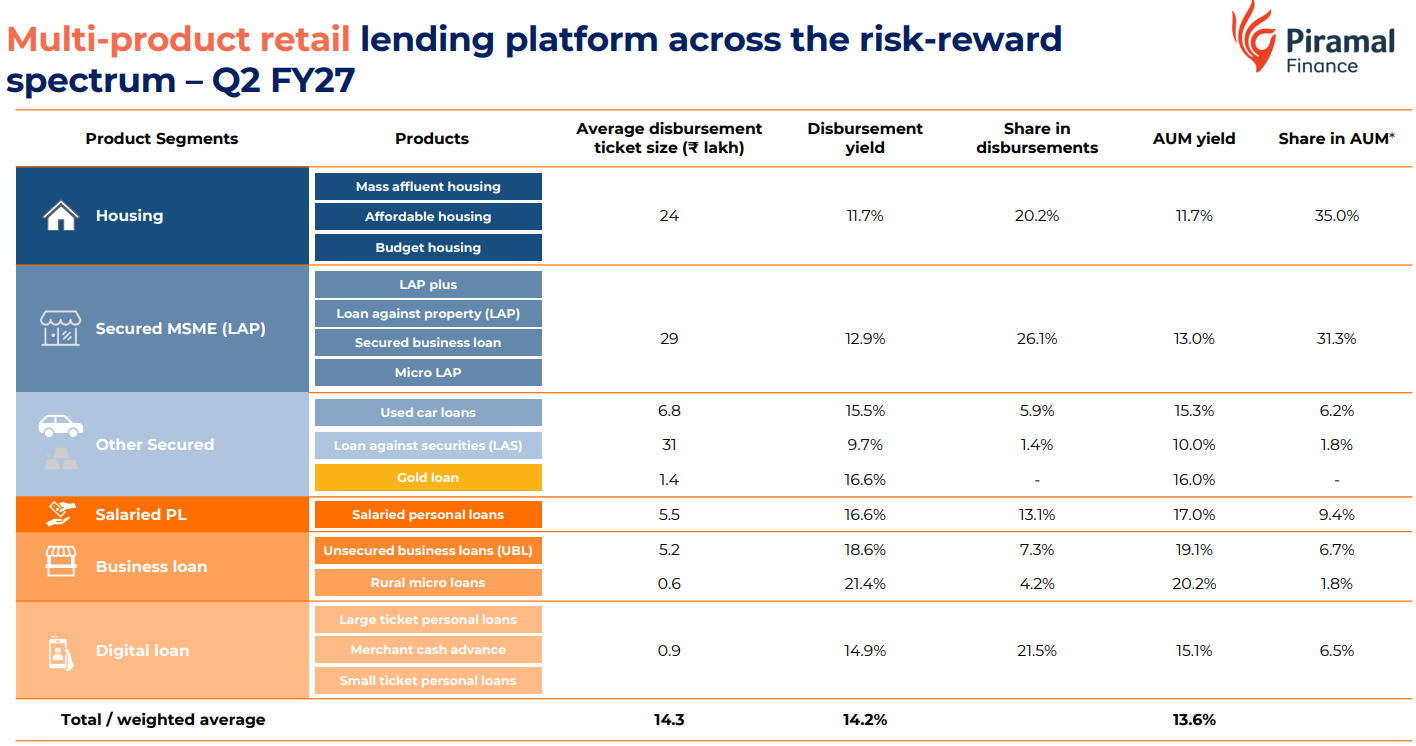
1. Retail Focussed NBFC
piramalfinance.com | NSE: PIRAMALFIN
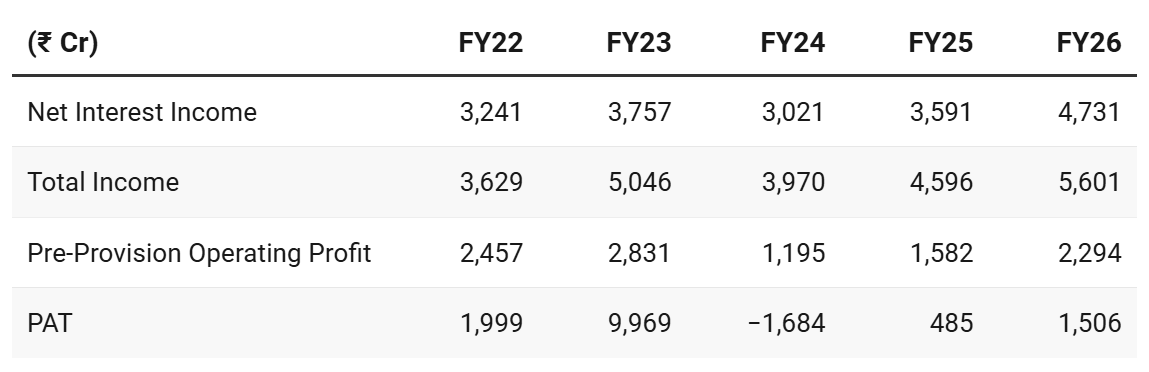
2. FY22-26: A period of transition
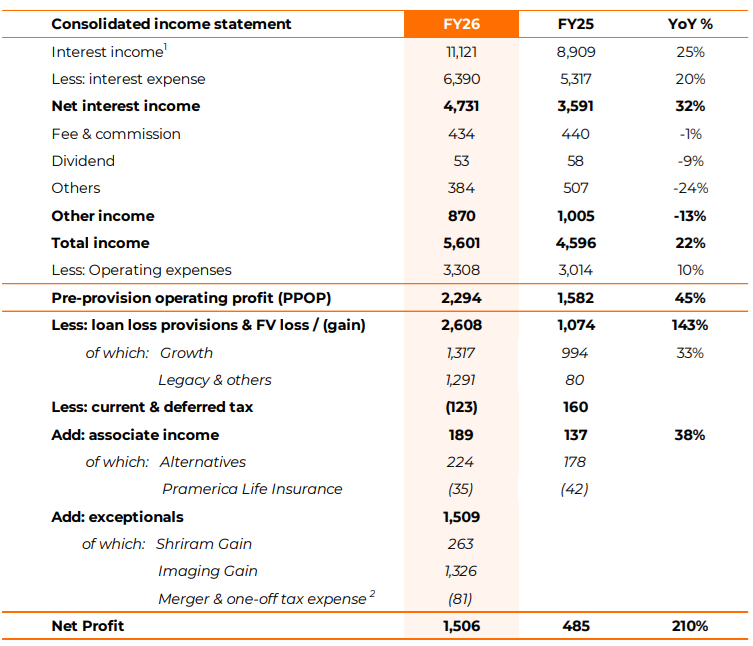
3. FY26: PAT up 210% & Net Interest Income up 32% YoY
4. Q2 FY27: PAT up 67% & Net Interest Income up 35% YoY
PAT up 8% & Net Interest Income up 6% QoQ
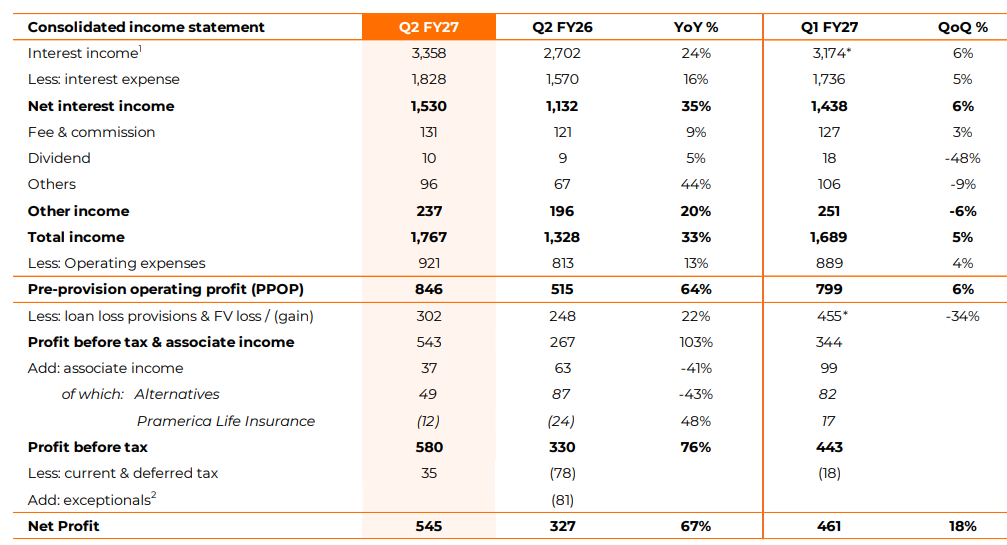
Capital Raise: ₹3,850 Cr capital raise during the quarter (₹2,100 Crore QIP +₹1,750 Cr promoter group warrants).
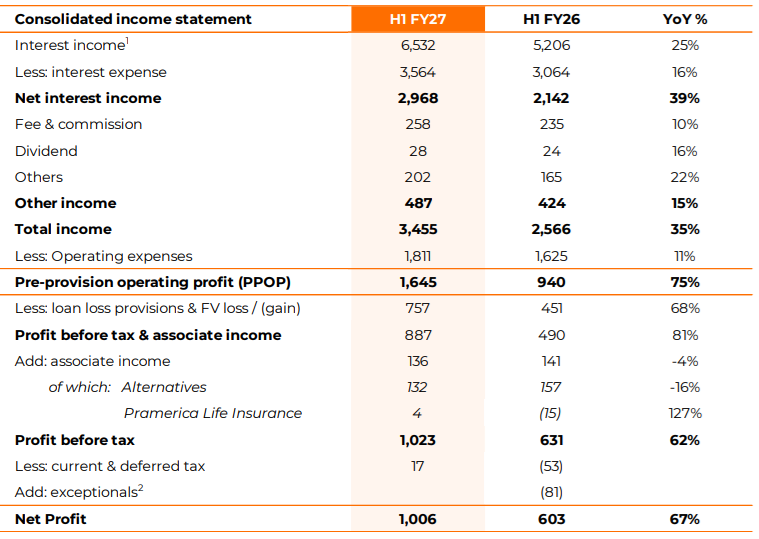
5. H1 FY27: PAT up 67% & Net Interest Income up 39% YoY
6. Outlook: 25% AUM Growth; 50% PAT growth
6.1 Management Guidance and Outlook
Bottom-line growth driven by improving profitability
AUM
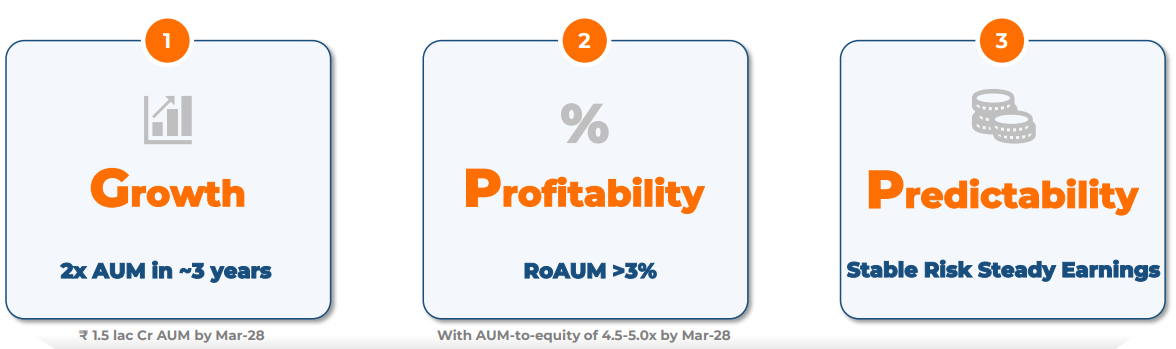
FY27 : 25% AUM growth
FY28: targeting ₹1.5 lakh crore
long-range blueprint to double AUM every 3 year i.e. 25% CAGR
FY27 Profit : 50% growth for FY27
RoAUM:
FY27: Annualized exit RoAUM of ~2.5% for Q4 FY27
Long-term goal remains >3.0% RoAUM.
Capital Adequacy
A ₹3,850 crore total capital raise (via ₹2,100 crore QIP and ₹1,750 crore promoter warrants), leverage (AUM-to-Equity) stood at 3.6x in Q2 FY27.
Leverage to expand toward goal of 4.5-5.0x by March 2028 as AUM scales.
Capital Runway at 20.1% — non-dilutive regulatory capital releases over the next 12 to 24 months — has ample capital runway to fund growth for several years.
Opex Efficiency: 25 bps reduction in opex-to-AUM guidance.
6.2 H1 FY27 Performance vs FY27 Guidance
On track to meet all FY27 targets
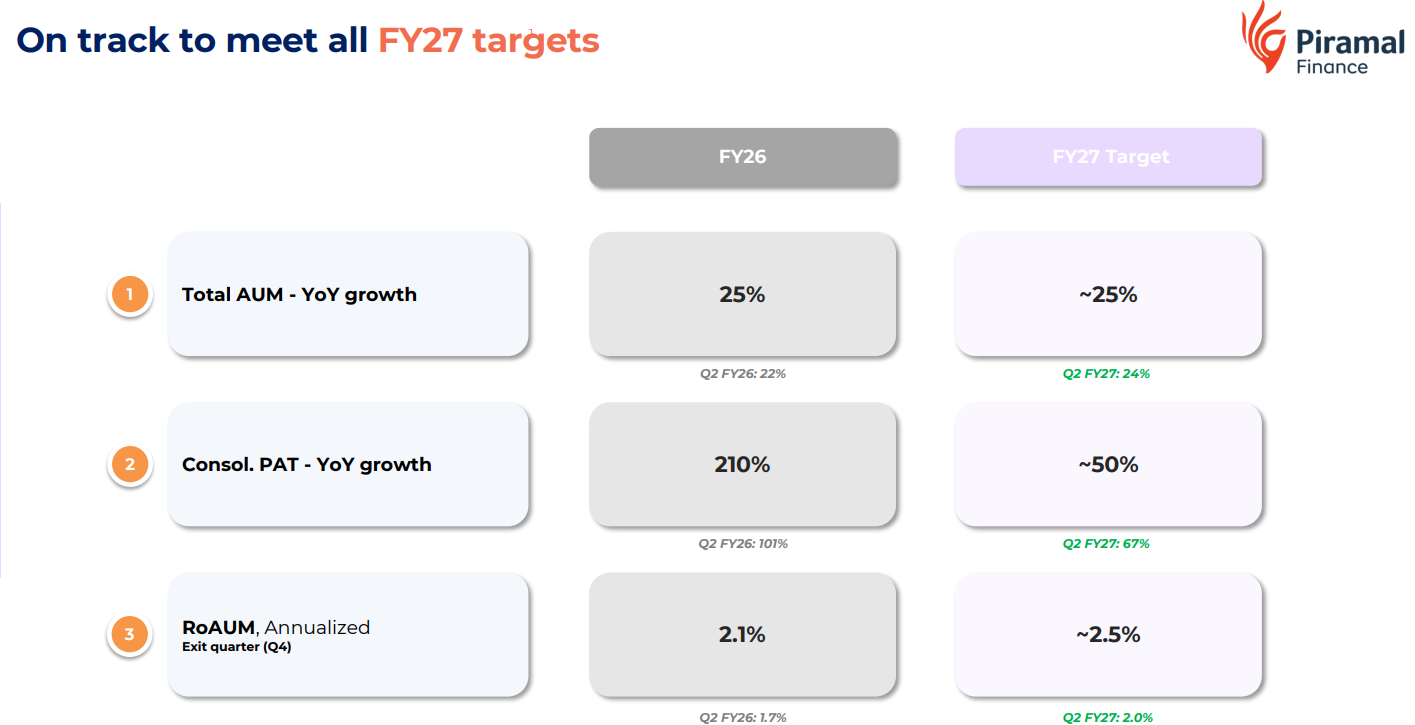
PAT growth of 67% is ahead of 50% growth guidance
Required run-rate to achieve FY27 target is high
Required quarterly run-rate for PAT the next 3 quarters is ~₹627 Cr vs the ₹545 Cr PAT delivered in Q2 FY27
6. Valuation Analysis
6.1 Valuation Snapshot — Piramal Finance
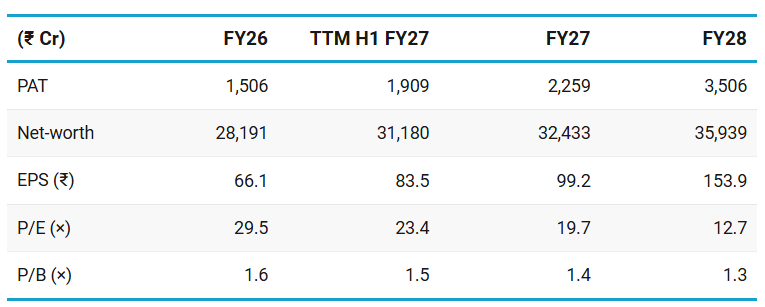
Current Market Price — ₹1,950
Market cap — ₹46,040 Cr
FY27 PAT = 1.5 X FY26 PAT
FY28 PAT =2.5% X average(FY26 AUM, FY27 AUM)
PIRAMALFIN trades at 1.5 P/B (×) on FY27 estimates.
For a company guiding to deliver 50% PAT growth with ROAUM closer to 2.5% — the P/B multiple provides an opportunity of re-rating closer to 2 P/B (×)
6.2 Opportunity at Current Valuation
Multiple Re-rating: Opportunity of being re-rated at around 2(×) P/B if FY27 guidance is delivered and PIRAMALFIN shows progress on executing FY28 guidance.
As leverage (AUM-to-equity) expands from 3.6x toward 4.5x–5.0x by FY28 end, Return on Equity (RoE) is projected to scale up, which typically supports higher P/BV multiples
Capital adequacy stands at 20.1%, meaning the FY28 AUM expansion to ₹1.5 lakh crore can be funded organically without equity dilution after the fund raise in Q2
6.3 Risk at Current Valuation
Execution Risk: PIRAMALFIN is on-track to deliver FY27 guidance. The challenge is to consistently deliver on the FY28 guidance.
Interest Rate Pressure:
RBI’s shift from a neutral stance to calibrated tightening
Expected to increase in borrowing costs in H2 FY27.
If borrowing costs escalate faster than loan repricing (given a ~1-year lag on PLR adjustments for home loans), net interest margins (NIMs) could face near-term pressure.
Global headwinds —elevated US and Japanese bond yields, persistent inflation, and high crude oil prices—could raise the overall cost of capital.
Industry-Wide Over-Leveraging in Gold Loans:
Management highlighted that over 35% of borrowers across product categories now hold an active gold loan (up from 20%–25% two years ago).
~₹4.7 lakh crore of gold loan disbursements across the industry in FY26 went to deep delinquent borrowers (90+ DPD).
Although Piramal excludes 90+ DPD customers from receiving gold loans, rapid branch expansion (targeting 200 gold branches by March 2027) carries operational and credit risk if broad industry delinquencies rise.
Emerging credit challenges persist in home loans for IT sector employees in South India.
Sequential uptick in 90+ DPD delinquencies was noted in Home Loans (HL), Loan Against Property (LAP), and Used Car loans.
Credit Cost Risk in Unsecured Scaling: Expanding higher-yielding unsecured loans (salaried personal loans, digital loans, business loans) to 25%–26% of Total AUM raises portfolio yield but increases loss severity if macro or micro-level credit stress develops.
Previous coverage on PIRAMALFIN

Don’t like what you are reading? Will do better. Let us know at hi@moneymuscle.in
Don’t miss reading our Disclaimer