
1. South India focused B2B jewellery manufacturer
deepajewel.com | NSE: DEEPA
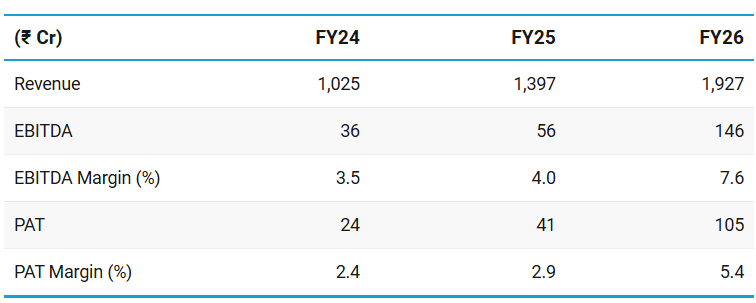
2. FY24-26: PAT up 108% & Revenue up 37% CAGR
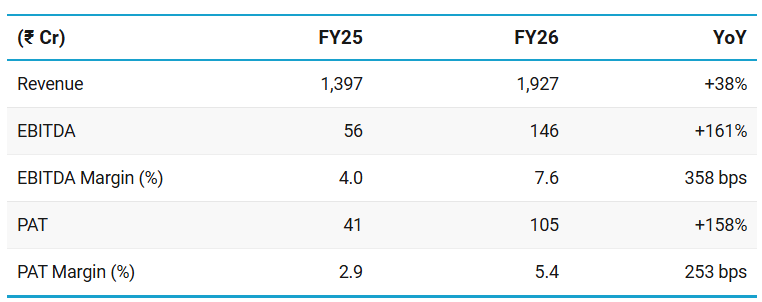
3. FY26: PAT up 50% & Revenue up 32% YoY
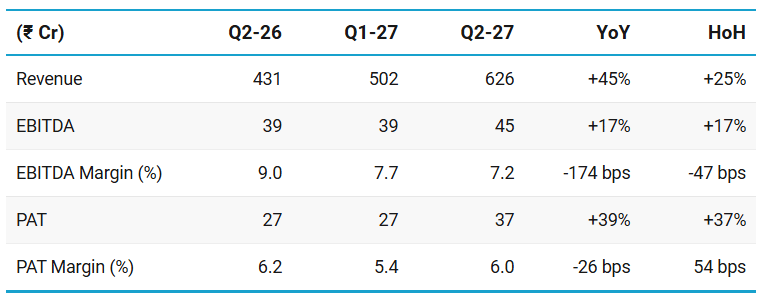
4. Q2 FY27: PAT up 39% & Revenue up 45% YoY
PAT up 37% & Revenue up 25% HoH
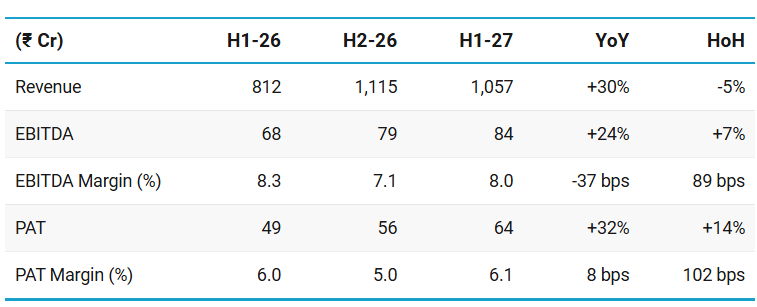
5. H1 FY27: PAT up 32% & Revenue up 30% YoY
PAT up 14% & Revenue down 5% HoH
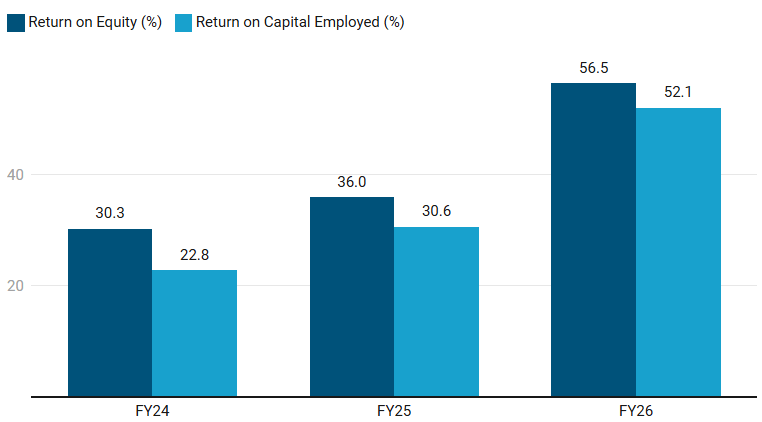
6. Business Metrics: Strong Return Ratios
7. Outlook: 40-45% Growth till FY29
7.1 Guidance & Future Outlook
Growth guidance based on volume growth of 40-45% as price has been assumed constant
For FY27, ‘28 and ‘29, we expect a CAGR growth of between 40%-45%.
We have taken the gold price to be constant at a rate of 24-karat rate of Rs. 50,000.
We expect about 80-120 bps increase in our EBITDA margins over a period of next 4-6 quarters.
Levers for Margin Expansion:
Newly opened Hyderabad manufacturing facility, lowers production costs compared to outsourced work.
Increasing the share of higher-margin studded jewellery from 57% in H1 FY27 to 75% over the next 3-4 quarters.
Foucs on Tier-2 and Tier-3 towns through new sales offices
Capture higher conversion margins from regional chains and standalone stores.
Continued expansion in job work, which carries high EBITDA margins (~75%) and requires minimal working capital.
Growth Levers:
New sales offices — Vijayawada (opended), Chennai (end of Q3 FY27), Bangalore around April–May 2027.
Expanding into Studded Casting, Nakshi, and Tapa jewellery, having introduced 16 new SKUs in Q1 FY27.
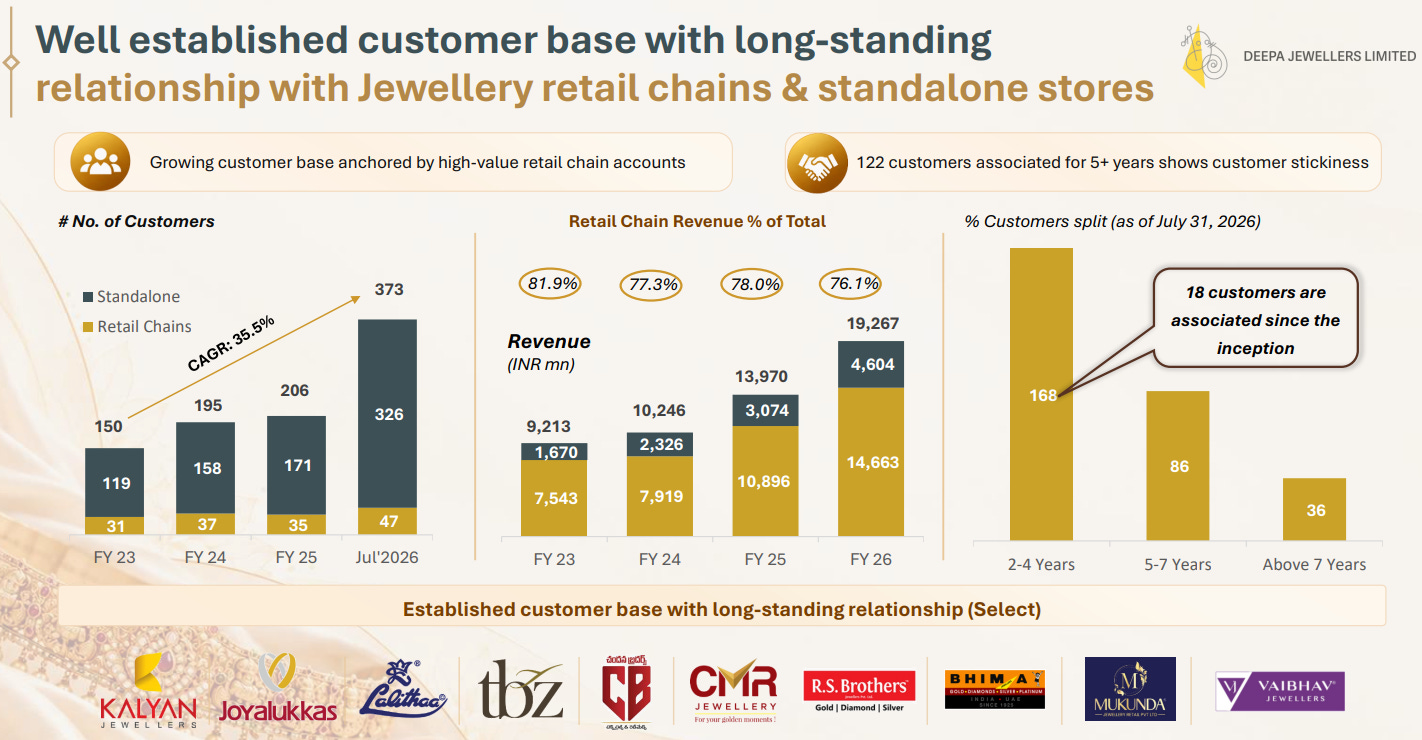
Supporting the rapid store and franchise expansion of major clients like Joyalukkas, Kalyan Jewellers, Lalitha, and Bhima through initial store filling and ongoing stock replenishments.
7.2 H1 FY27 Performance vs FY27 Guidance
H1 FY27 lagging FY27 guidance
Our business typically follows a seasonal pattern, with the first half contributing around 40% of annual revenue and a larger share accruing in the second half. The shift in festive demand into the second half along with the fresh issue proceeds is expected to support our growth trajectory in the second half of the financial year 2027.
H1 growth of 30% lags the 40-45% growth guidance given by DEEPA.
Management appears confident in its ability to catch up H2
8. Valuation Analysis — Deepa Jewellers
8.1 Valuation Snapshot
Current Market Price — ₹950
Market cap — ₹1,894 Cr
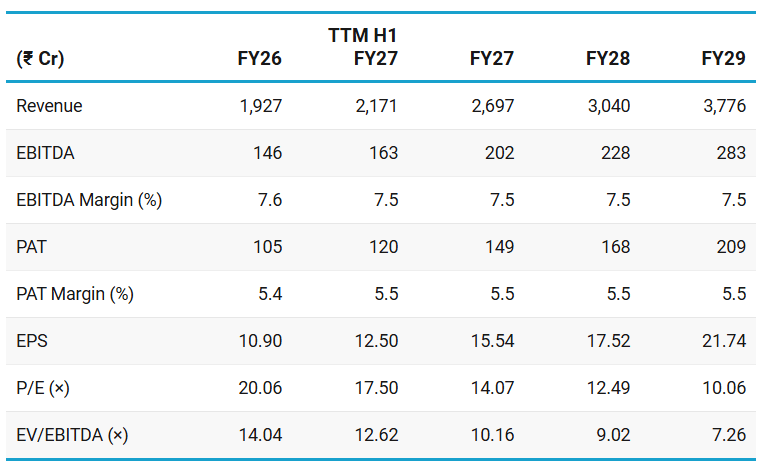
DEEPA looks attractive on FY27 earnings at a P/E of 18× and EV/EBITDA of 13× and if management delivers on the 40-45% growth target.
DEEPA starts looking even more attractive from FY28 onwards if the 40-45% growth with the 80-120 bps starts getting delivered.
If we assume a conservative 20× multiple on FY29 PAT of ₹200 Cr we arrive at a market cap of ₹4,000 Cr which is ~2×+ from the current market cap i.e. 40%+ CAGR opportunity.
8.2 Opportunities at Current Valuation
The 40-45% guidance has not been discounted at current valuations
The margin expansion accompanying the growth will add to the upside and has not been considered in the valuation analysis
The growth guidance is based on volumes not supported by and increases in underlying gold prices
8.3 Risks at Current Valuation
First time guidance given by the management of DEEPA
No track-record of DEEPA as a listed entity on its ability to deliver on its promises
While current valuations are such they can absorb a few quarters of weak performances on its journey towards FY29
Most of the risk lies in the ability of the DEEPA management to deliver on its guidance.
Help your group stay ahead. Share now!
Don’t like what you are reading? Let us know at hi@moneymuscle.in
Don’t miss reading our Disclaimer
PAT up 39% on revenue up 45% puts net margin at about 96% of last year's level (1.39 / 1.45), so the guided 80-120 bps EBITDA recovery first has to reverse that slip. Raising studded jewellery from 57% to 75% of the mix is the lever, and with gold held constant at Rs 50,000 the 40-45% CAGR depends on volumes, which makes quarterly volume growth the number to track.
with price held constant the guide rides on volume. q2 volume grew just 13%, all from job work while own processing and manufacturing stayed flat